The UMMC team is collecting socks through the month of October 2026 to benefit four local charities. See the flyer below if you would like to participate with us!
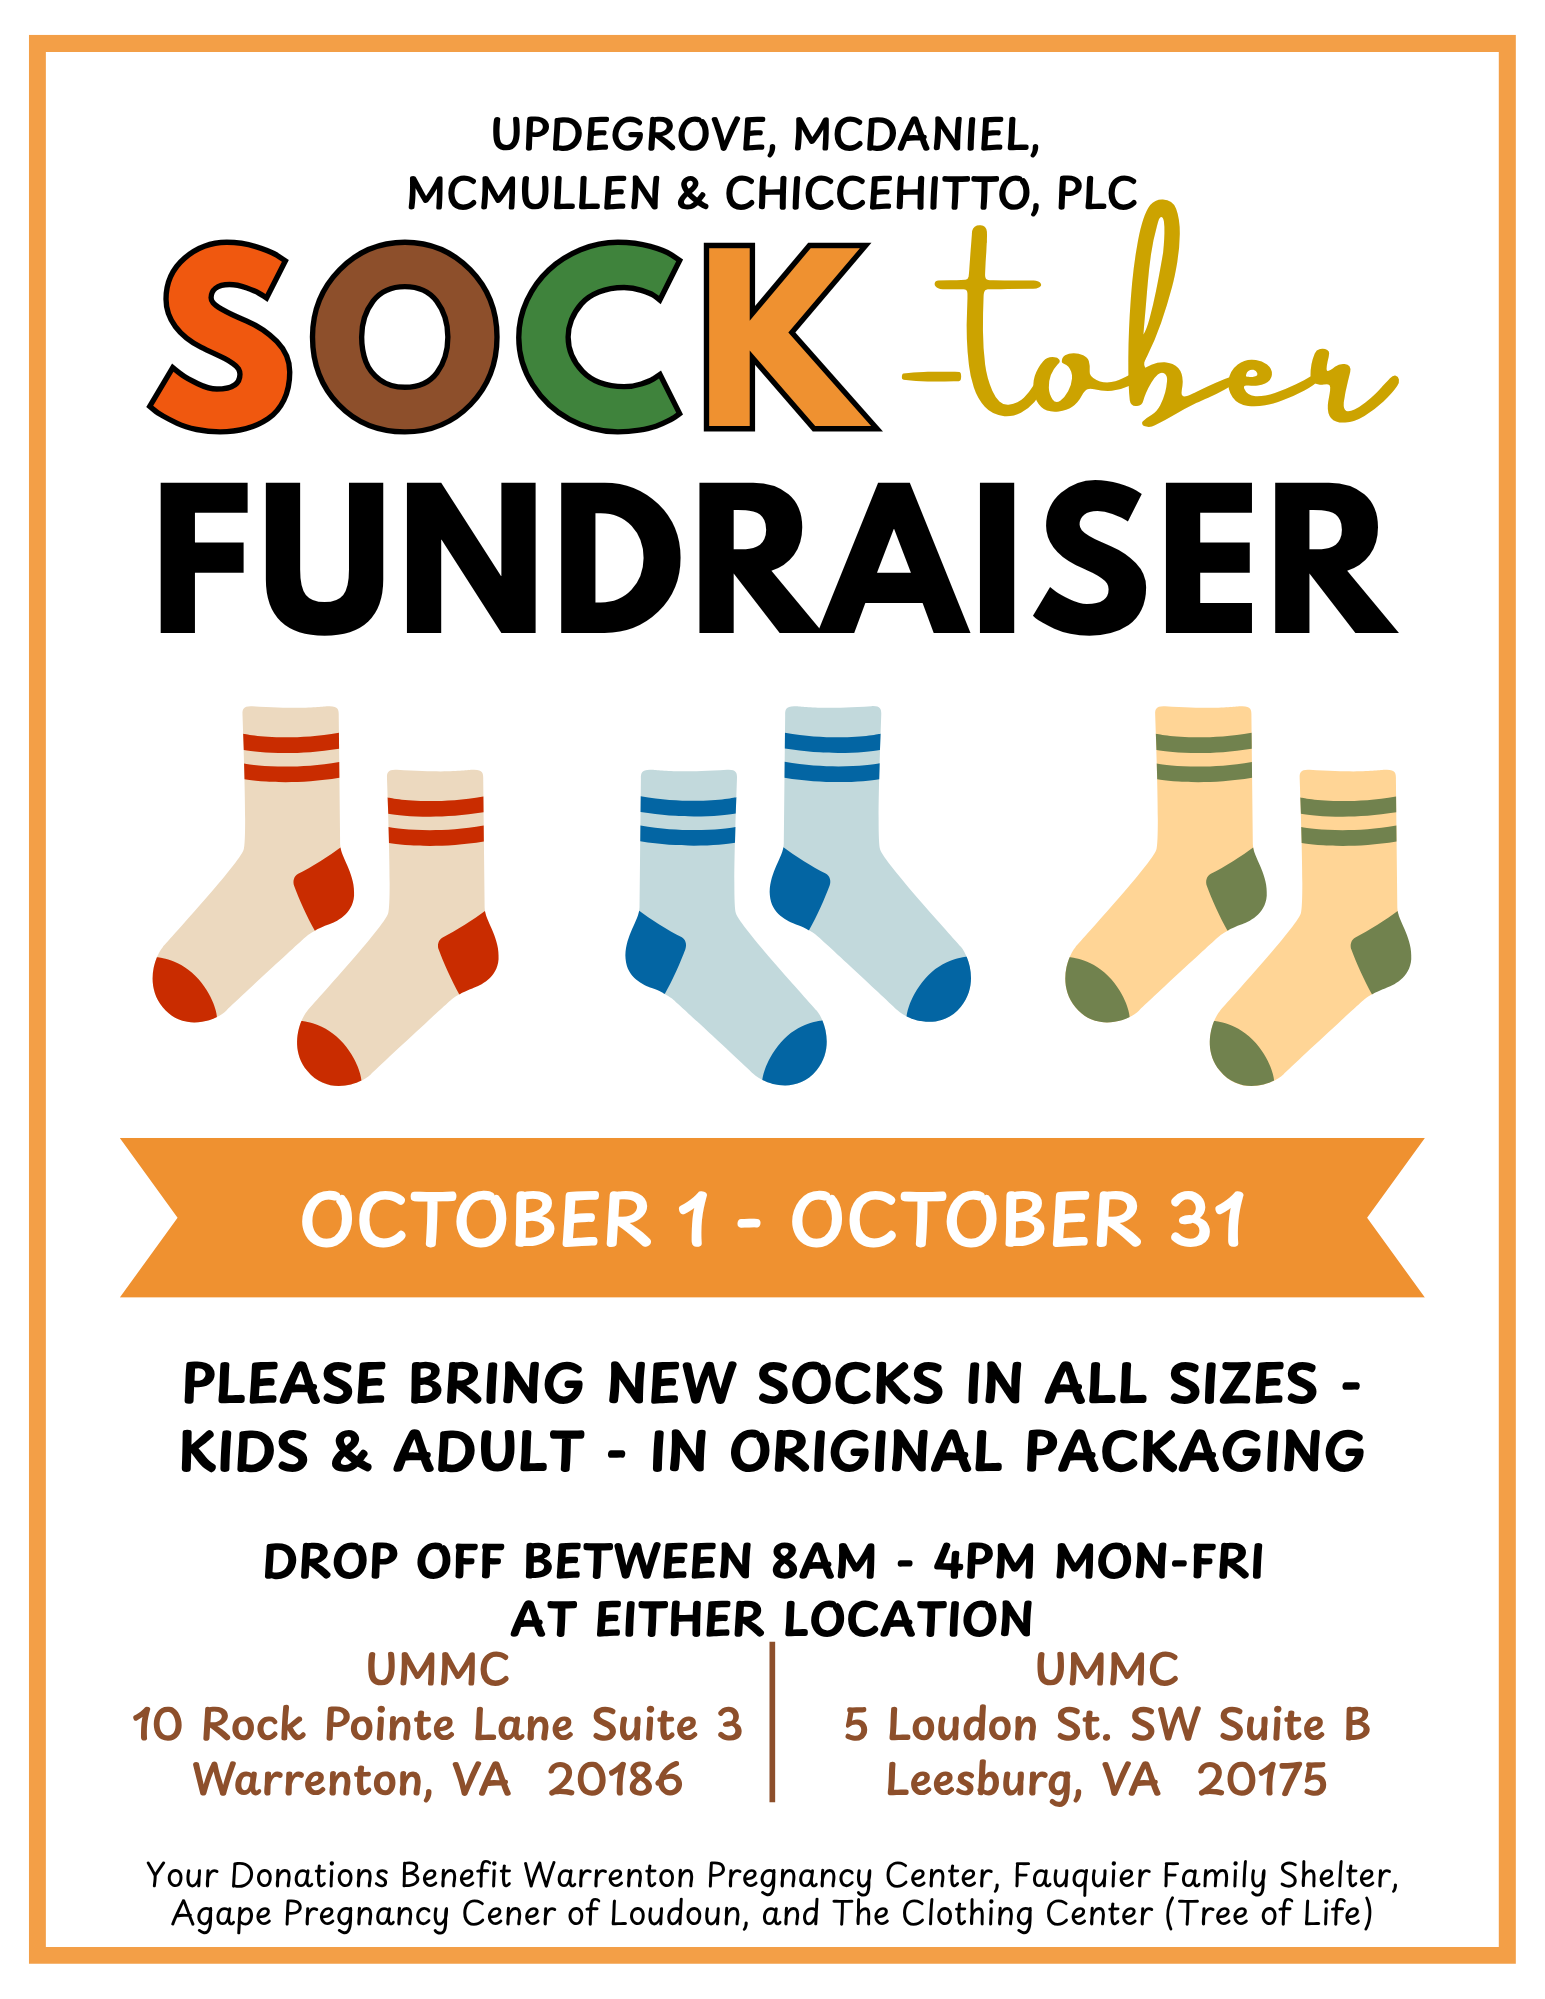
The UMMC team is collecting socks through the month of October 2026 to benefit four local charities. See the flyer below if you would like to participate with us!
2026 individual quarterly estimated Federal tax payments are due June 15, 2026, September 15, 2026, and January 15, 2027 for the remainder of the tax year.
The extended S corporation and partnership business tax deadline is September 15, 2026 and the extended individual and C corporation tax deadline is October 15, 2026. In order to meet these deadlines, UMMC must receive all information to prepare your returns by the dates identified below. If we do not receive all information needed by these dates, we cannot guarantee timely filings.
Documentation must be provided as follows:
S Corporations and Partnerships (with calendar year-end) – information will be needed by August 14, 2026.
Individuals and C Corporations (with calendar year-end) – information will be needed by September 14, 2026.
Nonprofits (with calendar year-end) – extensions are valid until November 16, 2026 and information will be needed by September 14, 2026.
The One Big Beautiful Bill Act (OBBBA) has fundamentally reshaped the tax-advantaged investment landscape by making the Qualified Opportunity Zone (QOZ) program permanent. For taxpayers sitting on significant capital gains in 2026, the strategy for when to sell and reinvest has shifted dramatically. Under the new OBBBA rules, waiting until 2027 to reinvest can unlock far superior benefits compared to the original framework.
The 2026 “Dead Zone” vs. the OBBBA Era – For several years, the tax benefits of the original Opportunity Zone program have been phasing out. While the core benefit of tax-free growth after 10 years remains, other incentives like gain deferral are nearing a “cliff.”
Under the original rules, any capital gain reinvested into a Qualified Opportunity Fund (QOF) must be recognized for tax purposes no later than December 31, 2026. This means that if you invest a gain today in a QOF, your tax deferral lasts less than a year. Furthermore, the 10% and 15% basis step-up benefits, which reduce the amount of deferred gain you eventually pay tax on, are currently unavailable for new 2026 investments because the required holding periods cannot be met by the fixed 2026 deadline.
Why Waiting Until 2027 Matters – The OBBBA introduces a rolling five-year deferral period for investments made on or after January 1, 2027. Instead of a fixed deadline, your deferred gain is recognized on the fifth anniversary of your investment date. Additionally, these new rules restore the 10% basis step-up for everyone who holds their investment for five years.
Taxpayers realizing gains in 2026 should consider structuring sales so that the 180-day reinvestment window falls in 2027, allowing them to bypass the “dead zone” of 2026 and qualify for the vastly superior OZ 2.0 incentives.
Unpacking the OBBBA Tax Benefits – The One Big Beautiful Bill Act (OBBBA) that became law on July 4, 2025, offers a powerful three-tiered tax incentive for investors who reinvest eligible gains into QOFs starting in 2027.
What Gains Qualify and How Much to Invest? One of the most common misconceptions about QOFs is that you must reinvest the entire sale proceeds. This is not the case.
Both short-term and long-term capital gains are eligible for reinvestment into a Qualified Opportunity Fund (QOF). The program does not distinguish between the two; essentially any gain that would be treated as a capital gain for federal income tax purposes qualifies for deferral.
Timing and the 180-Day Rule – Timing is the most critical component of QOF compliance. Generally, you have 180 days from the date of the sale that generated the gain to reinvest that gain into a QOF.
This flexibility is vital for 2026 planning. A gain realized by a partnership in early 2026 might still be eligible for QOZ investment in 2027 under the new OBBBA rules, provided the taxpayer uses the March 15 starting point for their 180-day window.
Where Are the Funds Invested? QOFs must invest at least 90% of their assets in Qualified Opportunity Zone Property, which includes:
How Do Taxpayers Invest in QOFs?
Estate Planning and Other Considerations – The QOZ program is an exceptional tool for both tax and estate planning.
If you are anticipating a major capital gain in 2026, the difference between an “end-of-year” sale and a “new-year” reinvestment could be worth 10% to 30% of your total tax liability. Please contact the Leesburg or Warrenton office if you have questions or would like to discuss your particular situation with a tax professional.
A child’s and their parent’s sports expenses, from registration fees and travel to equipment and volunteer time, sit at the intersection of personal, medical, charitable and business tax rules. For tax minded parents the key is sorting each cost into the correct box, documenting it carefully, and understanding the limited circumstances when a deduction or credit is available. This article walks through the major categories: possible child care treatment, charitable contributions and volunteer out of pocket expenses, medical expense exceptions, and when a child’s sport activity can be treated as a business.
As a Child Care Expense:
The child and dependent care credit (and associated employer provided dependent care benefits) is aimed at expenses that enable a parent (or parents) to work or look for work. Eligible care is generally custodial care for a qualifying individual, most commonly a child under age 13.
If a program combines athletic instruction and custodial care, only the portion of the cost allocable to custodial care is eligible. This requires reasonable allocation and substantiation in the event of a tax audit.
Charitable Contributions:
Donations to youth sports nonprofits and quid pro quo payments:
Volunteering Parents: Unreimbursed Out of Pocket Expenses:
Use of an Asset by a Charity: No deduction is allowed for mere use. Core rule: allowing a charity to use an asset you own (lending your field, permitting a nonprofit to use your boat, computer or home for activities) is not the same as donating the asset. The IRS generally disallows a charitable deduction for the value of the use of property.
Practical nuance: If you rent your property to a nonprofit at a below market rate, the difference between fair market rent and the amount charged could be considered a charitable contribution only in narrow circumstances and requires careful valuation and documentation; consult counsel.
Medical Expense Exception:
Prescribed activities for children with special needs may meet the definition of medical expenses that are primarily for the prevention or alleviation of a physical or mental disability or illness and may be deductible to the extent they exceed the floor (7.5% of adjusted gross income). The expense must be primarily medical in nature.
When a Child’s Sport Becomes a Business:
Profit motive matters. If a child participates in a sport with a bona fide profit objective (e.g., competing for significant prize money, endorsement deals, or providing paid coaching services), the activity could be a trade or business. In which case:
Income (prize money, sponsorships, appearance fees, Name, Image, and Likeness (NIL) deals for college athletes) is taxable.
Related ordinary and necessary business expenses are deductible against that income if the activity is carried on for profit. If the activity is classified as a hobby, expenses are not deductible.
Please contact the Leesburg or Warrenton office you if need assistance or would like to discuss your particular situation with a tax professional. Leesburg office 703-771-1818 or the Warrenton office 540-347-5681.
If your QuickBooks feels a little… off, you’re not alone.
Most business owners start the year strong, but by March or April, things begin to slip:
The good news? You don’t need a full overhaul.
With a few focused steps, you can clean up your QuickBooks in a single afternoon and avoid bigger problems later.
Step 1: Reconcile Your Bank and Credit Card Accounts
This is the foundation.
If your accounts aren’t reconciled, nothing else matters — your reports won’t be accurate.
What to do:
Common issues to look for:
If this step feels messy, that’s a sign cleanup is overdue.
Step 2: Clear Out “Ask My Accountant”
This account is meant to be temporary, not permanent storage.
What to do:
Why it matters:
Leaving items here can:
Step 3: Review Your Profit & Loss Statement
Now that your data is cleaner, check your numbers.
Go to: Reports → Profit and Loss
Look for:
Ask yourself: Does this reflect how my business actually performed?
If not, something still needs fixing.
Step 4: Fix Common Misclassifications
This is where a lot of hidden issues live.
Watch for:
These mistakes are extremely common, and they can directly impact your tax return.
Step 5: Check Your Balance Sheet (Yes, Really)
Most business owners skip this. Don’t.
Go to: Reports → Balance Sheet
Red flags:
Your balance sheet tells you whether your books are structurally sound, not just profitable.
Step 6: Review Your Accounts Receivable and Payable
Make sure you know:
Check:
This step alone can improve cash flow visibility immediately.
Step 7: Set a Monthly System (So You Don’t Have to Do This Again)
Once everything is cleaned up, the goal is to keep it that way.
A simple monthly routine:
Even 30–60 minutes per month can prevent hours of cleanup later.
When to Bring in a Pro
QuickBooks is powerful — but it doesn’t know if something is wrong, only if something is entered.
If you notice:
…it may be time to have a professional review your books.
QuickBooks problems don’t usually start big. They start small and grow quietly over time.
Taking a few hours now to clean things up can:
And the best part?
You don’t need to fix everything at once — just start with the steps above.
Please contact the Leesburg or Warrenton office if you have questions or would like to connect with a bookkeeper.
Updegrove, McDaniel, McMullen & Chiccehitto, PLC, (UMMC) with offices in Leesburg and Warrenton, Virginia, proudly celebrates its 50th anniversary of delivering excellence in accounting, tax, audit, and advisory services. Founded in July 1976, the firm has grown to become a trusted partner for individuals, businesses, trusts and estates throughout the region.
Over the past five decades, UMMC has built its reputation on integrity, professionalism, and a personal approach to client service. Today, the firm is led by partners Donna McMullen, Lisa Chiccehitto, Stephanie Mercer, Sarah Godfrey, and Mark Burgess, who continue to uphold the vision of client-centered, forward-thinking advice.
“Reaching our 50th anniversary is a tremendous milestone,” said Donna McMullen, Managing Partner. “We are grateful for the trust our clients place in us year after year and are committed to building on our legacy of dependable, expert service.”
For more information about UMMC and its five decades of client service, visit ucmcpas.com.